
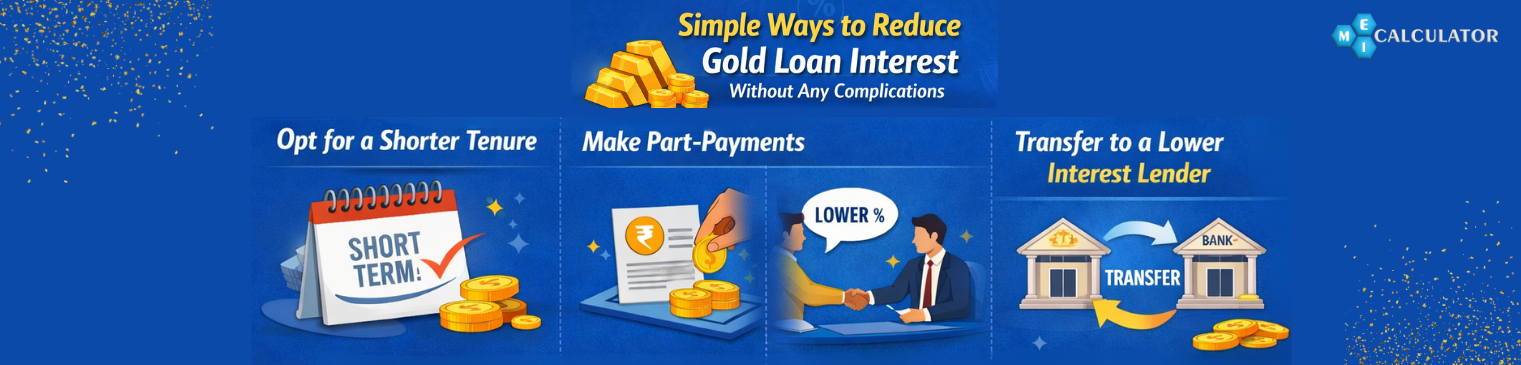
Simple Ways to Reduce Gold Loan Interest Without Any Complications
If you are thinking about taking a gold loan or already have one, lowering the interest can help you save a lot of money. Gold loans are popular because they are quick and require little paperwork. But this convenience can make it easy to forget about the total interest you pay.
Many people focus on getting the loan quickly and forget to check the total cost. The good news is you do not need to be a financial expert to lower your gold loan interest. A few simple choices can help you save money.
Know What Affects Gold Loan Interest
Before you try to lower your interest, it helps to know what affects it. Gold loan interest mainly depends on:
- The amount you borrow
- The interest rate charged by the lender
- The repayment period
- The repayment method selected
- Additional fees and penalty charges
Interest is charged on the remaining loan amount. So, the faster you pay down the principal, the less interest you will end up paying.
Borrow Only the Amount You Truly Need
One easy way to pay less interest is to borrow only what you really need. Many people take the full amount offered for their gold, even if they do not need that much.
This leads to higher interest because:
- Interest applies to the full loan amount
- A larger principal results in higher total repayment
It is best to figure out how much you need and add a small extra amount as a buffer. Borrowing less means you pay less interest and avoid extra repayment pressure.
Opt for a Shorter Loan Tenure When Possible
Gold loans are usually for short-term needs. Longer loan periods may lower your monthly payments, but they increase the total interest you pay in the end.
A shorter tenure:
- Reduces the duration for which interest is charged
- Helps lower total interest outgo
- Allows faster loan closure
If you can afford it, pick the shortest loan period you are comfortable with. Even cutting a few months can help you save a noticeable amount.
Select a Repayment Method That Reduces Interest
Gold loan lenders usually offer multiple repayment options, such as:
- Monthly EMIs covering principal and interest
- Paying only interest during the tenure and the principal at the end
- Lump-sum repayment at maturity
For most people, paying through EMIs is the best way to lower interest. As you pay each month, the loan amount goes down, so you pay interest on a smaller balance.
Many lenders let you make extra payments. If you get a bonus or extra income, using it to pay off part of your loan can really help.
Even one part-payment can:
- Lower future interest calculations
- Shorten the loan duration
- Reduce overall repayment pressure
Be sure to check the rules for early payments before you pay extra.
Compare Gold Loan Interest Rates Carefully
Gold loan interest rates are different at each bank and NBFC. Even a small change in the rate can save you a good amount of money.
Before finalising a lender:
- Compare offers from multiple institutions
- Ask about preferential rates for existing customers
- Check if rates depend on the loan amount
Checking and comparing interest rates before you take a loan is one of the best ways to lower your costs.
Do Not Ignore Additional Charges
Interest is not the only cost involved in a gold loan. Other charges may include:
- Processing fees
- Gold appraisal charges
- Renewal or extension fees
- Late payment penalties
These extra costs can add up without you noticing. Always ask for a full list of fees and include them when you compare loan offers.
Pay on Time to Avoid Extra Costs
If you pay late, you will have to pay extra fees and more interest. Missing payments often can also hurt your credit score.
To stay on track:
- Set payment reminders
- Use auto-debit facilities
- Maintain a small balance cushion in your account
Paying on time keeps your gold safe and helps you avoid extra interest.
Comparison Table: How Better Choices Lower Interest
| Scenario | Loan Amount | Tenure | Impact on Interest |
| Borrowing maximum eligible amount | ₹3,00,000 | 12 months | Highest interest cost |
| Borrowing only required amount | ₹2,50,000 | 12 months | Immediate interest savings |
| Choosing a shorter tenure | ₹3,00,000 | 9 months | Lower total interest |
| Making a part-payment | ₹3,00,000 | 12 months | Reduced interest after payment |
| EMI-based repayment | ₹3,00,000 | 12 months | Lower interest than lump-sum repayment |
Making these small changes can help you save thousands of rupees during your loan.
When Is Early Loan Closure a Good Idea?
If your finances get better sooner than you thought, paying off your gold loan early can be a good idea. This stops more interest from adding up and lets you get your gold back sooner.
Before doing so, check:
- Foreclosure or closure charges
- Net interest savings after fees
If you save more than you pay in fees, it is worth closing your loan early.
Final Takeaway
Lowering gold loan interest comes down to making smart choices. Borrow only what you need, pick the right loan period, pay back wisely, and watch out for extra fees.
A gold loan should help you, not cause long-term stress. With some planning, you can get money quickly and keep your interest costs under control.
